


Personal Wealth Management / Market Analysis
Putting Faster Money Supply Growth in Context
The recent uptick isn’t auto-inflationary.
Decades ago, Nobel laureate Milton Friedman taught that inflation is always and everywhere a monetary phenomenon: Too much money chasing too few goods and services. So with US money supply growth inching up from post-2022 lows, some pundits warn prices are about to gallop again. But hold your horses. Accelerating money supply growth doesn’t always amount to hot inflation tinder, making historical (and global) perspective necessary in weighing today’s fears. Look at money supply growth in this context, and it becomes apparent inflation fears fight the last war, a bull market hallmark.
America’s money supply growth has accelerated of late. Much of today’s chatter surrounds M2, which sums notes, coins, bank reserves, checking and savings accounts, money market funds and small time deposits. This is the broadest measure the Fed currently tracks, making it the most common headline measure. But we think M2 is too narrow, excluding several items that effectively function as money. We think better measures are M3, which also includes larger time deposits, institutional money market funds and larger liquid assets, or M4, which adds commercial paper and short-term government debt. While the Fed stopped publishing M3 and its broader “L” measure decades ago, the Center for Financial Stability tabulates M4.
Now to the data: M4 grew 7.4% y/y in August, slower than July’s 7.8% but extending a gradual, irregular acceleration from March 2025’s cool 4.3% growth rate.[i] August’s figure exceeds M4’s 5.9% y/y average monthly growth since data begin in January 1968.[ii] So there is more money sloshing around the system today, as seen in quick nominal (non-inflation-adjusted) GDP growth (8.0% annualized in Q2 versus 1.5% inflation-adjusted).
But is this too much for the economy to absorb without cranking consumer prices higher? As Friedman might ask, is all this new money fueling more goods and services production, or is it chasing a limited supply and raising prices?
A historical look provides some color here. While August’s 7.4% y/y is warmer, it is well below M4’s June 2020 pandemic era 30.5% peak, when the Fed deliberately injected massive new money into the economy while production was largely shuttered.[iii] Without equivalent stimulus today, M4 growth looks highly unlikely to return to those heights.
August’s rate is also quite common historically and not auto-inflationary. Exhibit 1 shows this by pairing M4 with the US CPI inflation rate, which tends to follow money supply at a roughly 12 – 18 month lag.
Exhibit 1: A Historical Look at Today’s Money Supply Growth

Source: Center for Financial Stability, as of 9/22/2026. Year-over-year percent change in M4 and US consumer price index, January 1968 – August 2026.
Back in the early 1970s, it took even hotter M4 growth, plus the OPEC embargo and the abandonment of price controls, to render the runaway inflation that contributed to 1973 – 74’s deep bear market. The hot inflation that prompted former Fed head Paul Volcker’s legendary tightening spree in the late 1970s and early 1980s also erupted from far stronger money supply growth than today’s.
M4 then exceeded today’s growth rates for large chunks of the 1980s and late 1990s, with inflation staying tame alongside a booming economy and markets. With massive business investment and GDP growth, faster money supply growth fueled production, not hot inflation. Today looks similar, with money supply growth fueling investment in AI-related infrastructure, energy grid buildouts and more. This investment is quite broad, with 62.1% of S&P 500 companies growing capital expenditures in Q2.[iv] It isn’t just AI, contrary to many folks’ perceptions.
Beyond this, an underappreciated fact is that money crosses borders easily, making inflation trends global and thus global money supply the swing factor. Yet broad money supply growth is rather tepid outside the US, which Exhibit 2 shows. Across the developed world, money supply growth is at or below its long-term average and well short of COVID highs.
Exhibit 2: A Global Tour of Money Supply Growth
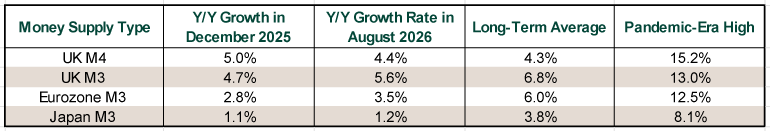
Source: Bank of England, ECB and St. Louis Fed, as of 9/29/2026. UK M4 (excluding intermediate OFCs), June 2010 – August 2026 and UK M3 (excluding intermediate OFCs), October 1987 – August 2026. Eurozone M3, July 1981 – August 2026. Japan M3, January 1981 – August 2026. We reference UK M3 as well as M4 here for its longer history.
Meanwhile, productive capacity looks healthy globally—helping supply businesses with goods and services, disincentivizing price hikes. See August’s PMIs, which saw manufacturing production, services sector business activity and new orders above the 50 line separating expansion and contraction in all these places—a sign production and consumption are up. Or see rising business investment in Q2 GDP in the US, UK and eurozone, suggesting businesses are deploying capital to keep goods and services flowing to meet demand.[v] Or see mostly positive month-over-month industrial production growth in the US, UK and Japan this year (the eurozone is more mixed).[vi] Or strong UK services output year to date.[vii] Or or or. There are abundant data showing global goods and services production and consumption are in fine fettle.
Thus, pundits’ sweating a minor uptick in global money supply reeks of fighting the last war, seeking a repeat of the last bear market’s presumed cause. That is standard investor behavior and a sign of skeptical sentiment, and it creates positive surprise potential when the other shoe fails to drop. Benign inflation looks likely to accomplish this.
[i] Source: Center for Financial Stability, as of 9/29/2026. Year-over-year change in M4 including Treasuries, January 1968 – August 2026.
[ii] Ibid.
[iii] Ibid.
[iv] Source: FactSet, as of 9/29/2026. Year-over-year total capital expenditure growth by S&P 500 constituent, Q2 2026.
[v] Ibid. Statement based on Q2 2026 quarterly GDP reports in the US, UK and eurozone.
[vi] Ibid.
[vii] Source: Office for National Statistics, as of 9/29/2026. UK Index of Services, month-over-month growth, December 2025 – July 2026.
If you would like to contact the editors responsible for this article, please message MarketMinder directly.
*The content contained in this article represents only the opinions and viewpoints of the Fisher Investments editorial staff.
Get a weekly roundup of our market insights
Sign up for our weekly e-mail newsletter.
You Imagine Your Future. We Help You Get There.
Are you ready to start your journey to a better financial future?
Where Might the Market Go Next?
Confidently tackle the market’s ups and downs with independent research and analysis that tells you where we think stocks are headed—and why.
Related Resources
-
Behavioral Finance Low Vibes Aren’t Keeping America’s Economy Down2026-09-29
-
Market Analysis Putting Faster Money Supply Growth in Context2026-09-29
-
Weekly Wrap-Up Fisher Investments Reviews: Last Week in Markets — September 21 - September 252026-09-28
-
Expert Commentary 3 Things You Need to Know This Week | US Jobs, Global Inflation, Midterm Miracle
 2026-09-28
Learn More
Learn why 210,000 clients trust us to manage their money and how Fisher Investments and its affiliates may be able to help you achieve your financial goals.
As of 6/30/2026
New to Fisher? Call Us.
Contact Us Today